 PT
 EN
 FR
 ES
 JA
 KO
 ZH
 AR
 FA
 RU
 NL
 MS
 VI
 PH
 TH
 ID


US elections could shake the markets
The USD continued to weaken in the FX market yesterday. The US midterm elections are in the market’s focus, as nothing less than US President Trump’s total control over the US administration is being set into doubt. Currently Republicans control both chambers of the US Congress allowing for US President Trump’s policies to pass into law, with a relative ease. Yet polls seem to show that the Democrats may be able to flip one if not both Chambers of Congress. Thus, the high stakes are also accompanied by high uncertainty about the outcome, making the elections an explosive mix for the markets.
US tech shares continue to lose ground
US tech shares continued to slide lower as market worries for the amount of investment required for AI development are maintained. Should the market worries intensify we may see tech shares continuing to slide lower and vice versa. Apple’s EPS and revenue figures reported, were higher than expected, yet the company’s share price dropped later on. Palantir’s share price seems to be supported as it also outperformed market expectations with its earnings report. Anthropic has amended its S-1 investor prospectus raising its revenue figure, which could intensify market interest in its upcoming IPO, boosting its price.
Oil prices correct higher as the market hesitates
Oil prices corrected higher in today’s Asian session as market hopes for a possible Qatari diplomatic breakthrough in the US-Iran conflict have dimmed. The US attacked Iran’s Qeshm Island, while Iranian officials stated that the two sides are still far from reaching a deal that could end the conflict. A possible intensification of the market’s worries could lift oil prices and vice versa.
Other highlights for today
In today’s American session, we note that ECB Board Member is scheduled to speak, while in the US we get the factory orders and JOLTS job openings figure for September, the weekly API crude oil inventories figure, while later on we get New Zealand’s Q3 employment data. In tomorrow’s Asian session, we get Australia’s Final Composite PMI figure for October, Australia’s Household spending for September and in the European session, we get the Czech Republic’s preliminary CPI rates for October, Euro Zone’s and the UK’s final Services and composite PMI figures for October, Euro Zone’s Preliminary HICP rates for October, while in Sweden Riksbank is expected to hike rates.
Charts to keep an eye out
XAU/USD Daily Chart
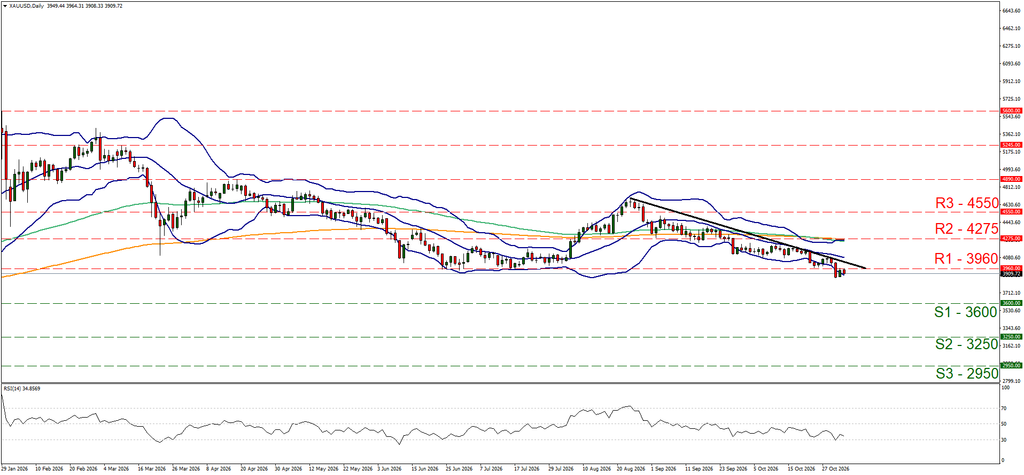
Resistance: 3960 (R1), 4275 (R2), 4550 (R3)
Given the US elections on a technical level, we keep a close eye on Ouro’s chart. XAU/USD’s price seemed to stabilise just below the 3960 (R1) resistance line. We maintain our bearish outlook for the precious metal’s price, as long as the downward trendline guiding it remains intact. The RSI indicator remains at low levels, just above 30, implying a strong bearish market sentiment for gold’s price. Should the bears maintain control over the index, we may see it aiming for the 3600 (S1) line. Should the bulls take over, we may see gold’s price rising above the 3960 (R1) resistance line, continue to break the prementioned downward trendline ending the downward motion, and continuing higher aiming if not breaching the 4275 (R2) resistance level.
US 100 Cash Daily Chart
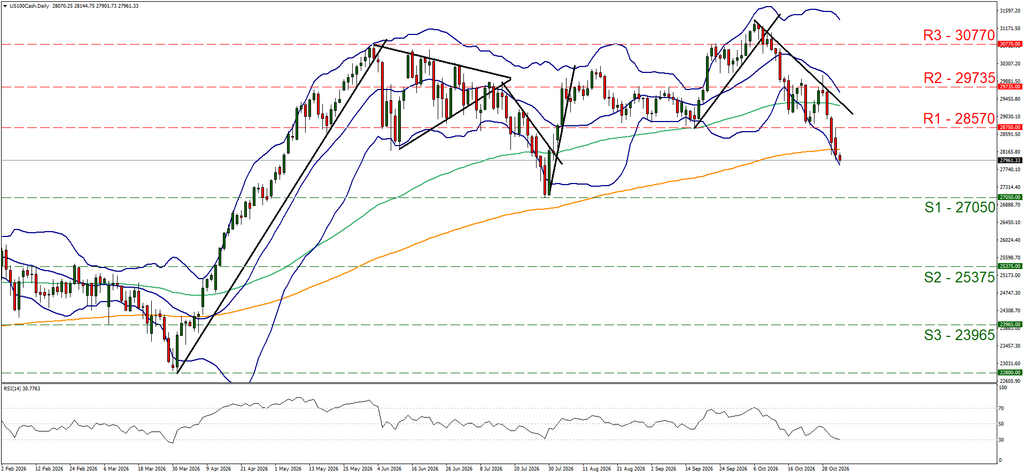
Resistance: 28570 (R1), 29375 (R2), 30770 (R3)
Nasdaq’s price action continued to drop aiming for the 27050 (S1) support line. We maintain our bearish outlook for the index given also that the RSI indicator has reached the reading of 30 implying a strong bearish market sentiment for the index. Should the bears remain in charge of the index’s direction, we may see Nasdaq reaching if not breaching the 27050 (S1) support line. Should the bulls take control, we may see Nasdaq reversing the losses of the past three session, breaking the 28570 (R1) resistance line and aim for the 29735 (R2) resistance level


