 AR
 EN
 FR
 ES
 JA
 KO
 PT
 ZH
 FA
 RU
 NL
 MS
 VI
 PH
 TH
 ID


USD – Fed’s minutes to get attention
In maybe the most characteristic move in the FX market over the past week the USD was in the greens for a third week in a row. A tighter US employment market for October and high inflationary pressures still being present in the US economy, all tended to enhance the market’s expectations for the Fed to tighten its monetary policy at a faster pace. Its characteristic that Fed Board Governor Waller opened the door tto a double rate hike in the December meeting. Currently FFF imply a probability for the Fed to hike rates by 25 basis points (bp) in December of 90.8%, while the market also seems to expect another rate hike in the January meeting.
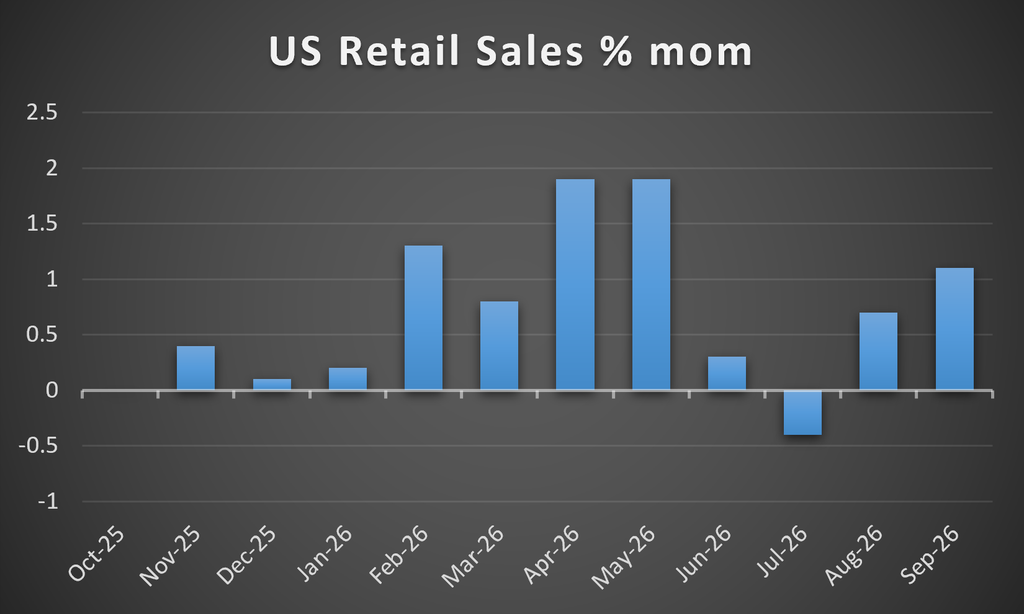
As the Fed’s intentions are in the epicenter of the market’s attention currently, we highlight the release of the FOMC’s October meeting minutes, next Wednesday. The document is expected ot be scrutinised by traders and analysts alike in search of further clues regarding what the intentions of the bank and its policymakers. Should we see the balance of power within the bank shifting even furthher towards the hawkish side, we may see the USD getting some support while at the same time gold’s price may lose ground. Vice versa, should the document be characterised by a less than expected hawksih tone we may see the USD losing groundas the market may caught by surprise and may forced to re-adjust its hawkish expectations by selling the USD.
GBP – Employment data and CPI rates could move the Sterling
The GBP is clearly losing ground against the USD and the EUR, yet seems to stable against the JPY as the week draws to a close. On a monetary level, BoE is expected to hike rates by 25 bp on the 17th of December, which tends to be supportive for the GBP. Yet our attention in the coming week is to be on macroeconommics. Two financial releases stand out, the first being the UK employment data for September on Tuesday and a possibly tighter UK employment market could provide support the GBP.
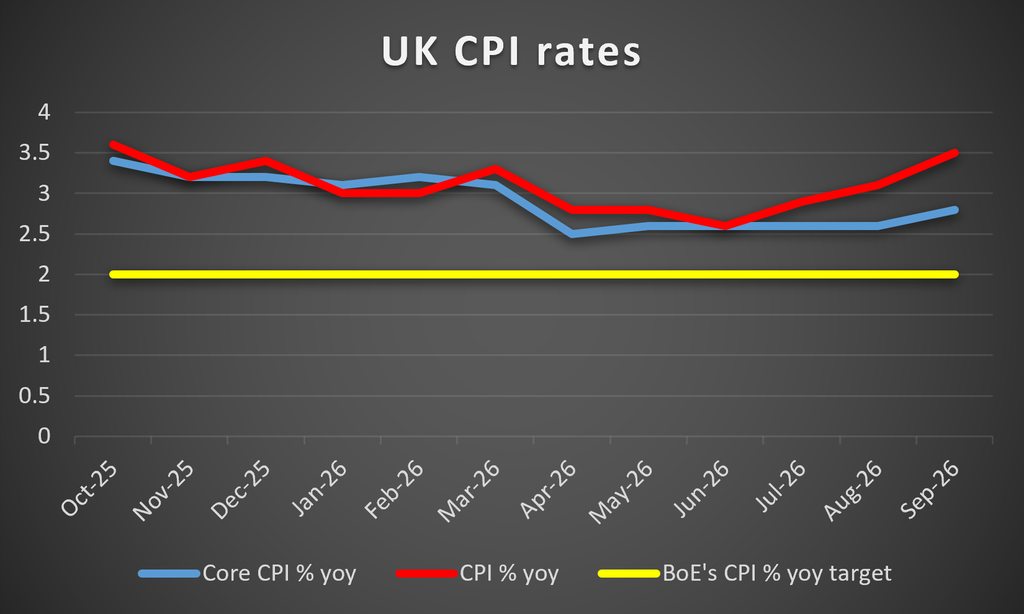
The following day we get UK’s CPI rates for October and a possible acceleration could add more pressure on BoE to proceed more decisively with tightening its monetary policy, thus also supporting the GBP. Also we note the release of UK’s retail sales growth rate for October, and should the rates show a styronger demand side in the UK economy we may see the GBP gaining. On a fundamental level, we highlight the UK-EU summit which is to take place in Brussels, next Friday. Should there be signs of a tightening of the UK-EU relationswhips we may see the GBP getting some support and vice versa.
JPY – Q3 preliminary GPD and October’s CPI rates eyed
JPY is about to end the week, understandably weaker against the USD and to a lesser degree against the EUR yet remains rather stable against the GBP. At a monetary level, we note that the market expects the bank to hike rates by 25 bp and JPY OIS currently imply a probability of 73% for such a scenario to materialise. The summary of opinions for the bank’s latest meeting in October, suggests that the majority of BoJ policymakers tend to lean more on the hawkish side. Yet BoJ board member Asada pushed back against “early rate hike” calls, underscoring his dissent.
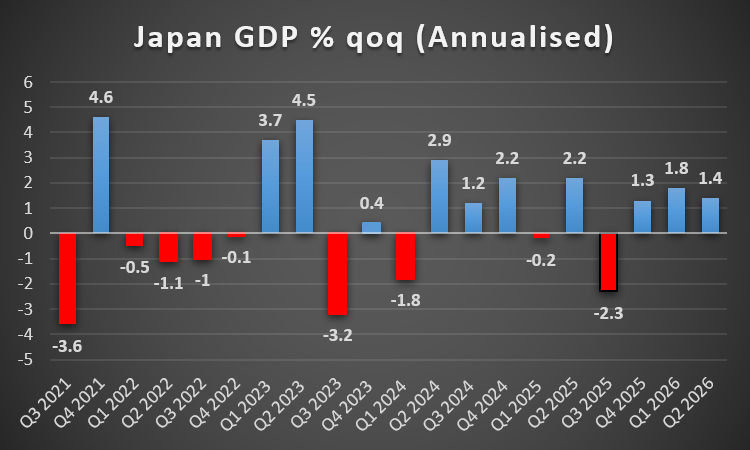
We note on Monday’s Asian session, the speech of BoJ Board Member Hajime and overall, should we see BoJ policymakers expressing hawkish views we may see the JPY getting some support. On a macroeconomic level, we note the release of Japan’s preliminary GDP rate for Q3, on Monday. The rate is expected to slow down considerably, which could weigh on the JPY as it would imply a slower pace of expansion for the Japanese economy. We also highlight the release of Japan’s CPI rates for October and should the rates slow down, we may see JPY slipping as it would imply an easing of inflationary pressures in the Japanese economy, thus setting the narrative of BoJ for the necessity of rate hikes into doubt, thus weighing on the JPY.
EUR – Fundamentals to lead the common currency
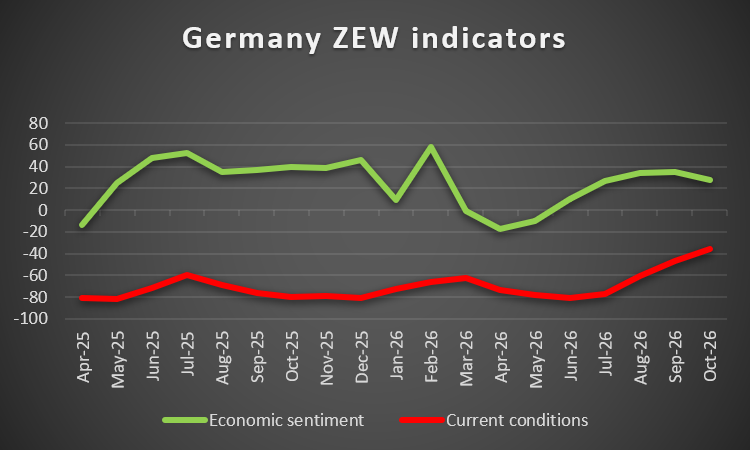
The single currency seems about to end the week lower against the USD, gains against the GBP and JPY. In the coming week there are only few high impact releases related to the EUR. Among which we note the release of the release of Euro Zone’s industrial output for September, Germany’s ZEW indicators for November and Euro Zone’s final HICP rates for October. On a monetary level, the ECB is expected to hike rates in the December meeting which tends to be supportive for the EUR. Despite a number of analysts highlighting the rate hike to come as the last one, we still see the case for more monetary policy tightening to come, in H1 27,as inflationary pressures, may prove to be more persistent for the Euro Zone.
any signs of tightening relationships between the UK and the Euro Zone may provide some support for EUR as well.
AUD – RBA’s minutes and October’s employment data in focus
AUD seems to continue to be in the reds against the USD after last week’s tumbling. On a monetary policy level, we note the market’s expectations for RBA to remain on hold. In the coming week we note the speech of RBA Governor Bullock in Tuesday’s Asian session, yet we highlight in the same session the release of RBA’s November meeting minutes. On a macroeconomic level, we note the release of Australia’s employment data for October, next Thursday. Should the data show a loose employment market in Australia, we may see the Aussie losing ground, as the hesitation of RBA to proceed with monetary policy tightening may grow.
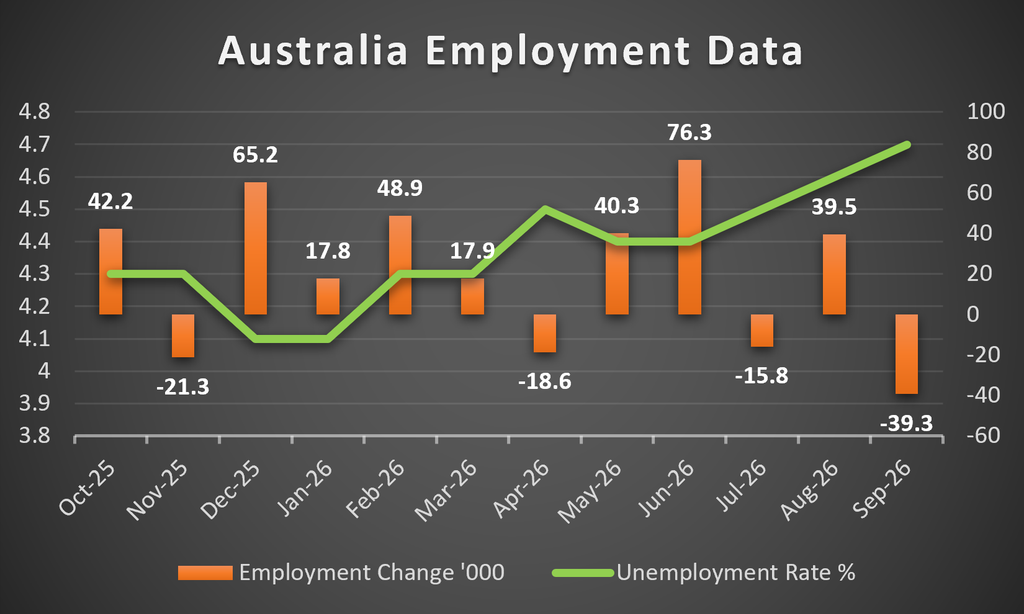
Other than that we also note on a deeper fundamental level the role that the market sentiment could play on the AUD’s direction. A possibly more risk on market sentiment could provide some support for AUD which is considered as a more risky asset in the FX market. Conversely a possible risk-averse market sentiment could weigh on AUD. Last but not least we also note the slew of data awaited from China on Monday’s Asian session, given that Australia exports a substantial amount of raw materials to China. Thus a possible acceleration of the rates could be translated to good news for Australian exporters thus providing some support for the AUD.
CAD – Canada’s October CPI rates to shake the Loonie
The Loonie is about to end another week, deep in the reds against the USD. On a monetary level, the market seems to expect BoC to hike rates, in the December meeting, which tends to be supportive for the Loonie on a monetary level. Currently CAD OIS imply a probability of 64.9% for such a scenario to materialise. Yet the monetary outlook of BoC continues to be weaker than the Fed’s, allowing for interest rate differentials to support USD/CAD. On Wednesday we note that BoC Deputy Governor Gravelle speaks and should he adopt a hawkish tone we may see the Canadian Dollar getting some support.
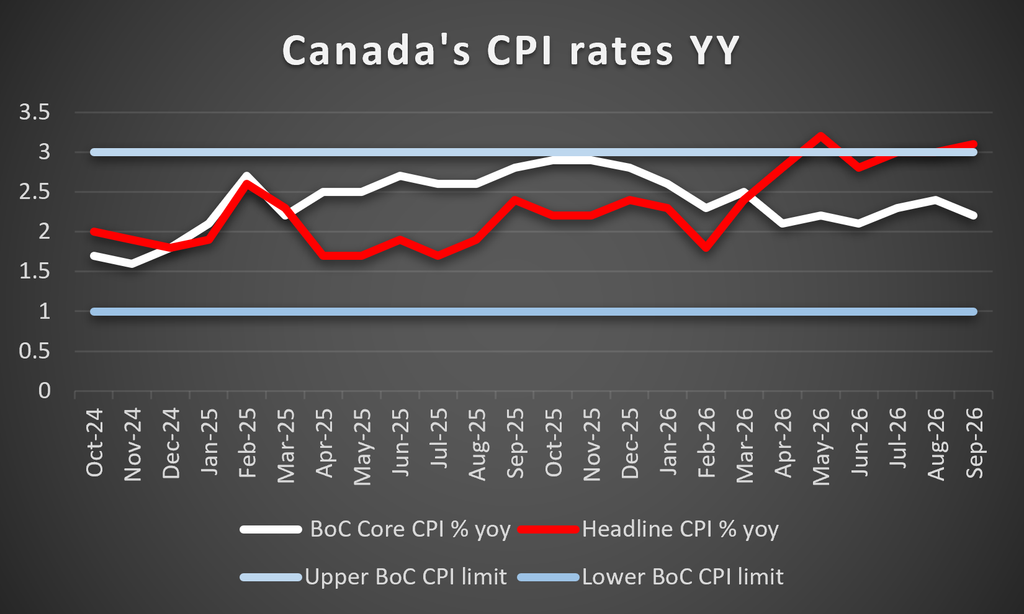
Hence on a macro economic level, we highlight on Monday the release of Canada’s CPI rates for October. Should we see an acceleration of the CPI rates, possibly distancing to the upside, from BoC’s 1-3%yy inflation tolerance zone, we may see the market’s hawkish expectations intensifying, thus providing some support for the Loonie. We also note for CAD traders, the release of the PPI rates for October on Thursday and on Friday we get Canada’s retail sales for September. Also on a fundamental level we note the role of the market sentiment may have on the direction of the Loonie. A possibly cautious market sentiment could weigh on the CAD and vice versa, a possible more risk oriented market sentiment could allow for the Loonie to post some gains. in the coming week as well.
DISCLAIMER: This content is for general informational and educational purposes only and should not be considered investment advice or investment recommendation.


